The recently published frontline retail protocol for separating scrap gold from resalable inventory, developed to help jewelers avoid leaving margin on the melting table, is far more than a procedural guide for buyback counters. For B2B wholesale and manufacturing stakeholders, the framework is a clear signal of structural shifts across the $380 billion 2026 global jewelry market, driven by volatile precious metal pricing, circular policy mandates, and fast-evolving consumer preferences that are rewriting long-held rules for which pieces hold value beyond their raw metal weight.
The trend’s origins stretch back to 2024, when spot gold prices began a sustained 21% climb that pushed solid gold entry-level jewelry price points out of reach for 62% of Gen Z and millennial shoppers, per 2026 Jewelers of America data. For years, retailers running gold buyback programs operated on a simple calculus: test purity, pay 80-90% of melt value, send all inventory to refiners for processing. But as gold prices rose, retailers began noticing that pieces once written off as “unfashionable” — chunky curb chains, engraved signet rings, cubic zirconia-accented pendants from the early 2000s — were selling for 2-3x their melt value when listed as vintage or archival pieces, while misidentified gold-filled, plated, or weighted pieces were cutting into scrap margins by as much as 15% when sorted incorrectly. The new sorting protocol formalizes what top-performing retailers have already learned: treating every buyback item as raw metal erodes profit, while uncritical acceptance of marked purity carries unacceptable risk.
Gen Z’s growing preference for circular, long-wear pieces is the core force expanding the definition of resalable inventory beyond high-karat heirloom pieces. Unlike previous generations that viewed pre-owned jewelry as a budget compromise, 58% of Gen Z jewelry shoppers actively seek out styles with vintage or archival character, aligning with broader fashion trends leaning into Y2K revival, 2000s hip-hop culture, and understated quiet luxury. This shift has also altered material demand: thin, fast-fashion gold-plated pieces that tarnish within 6 months have no resale value and are almost always routed to scrap, while durable, tarnish-resistant materials that retain their finish for years are increasingly sorted for resale, even when they contain no solid gold. That shift has driven double-digit 2026 growth in 316L stainless steel jewelry and 925 silver jewelry, which deliver the same visual appeal as solid gold at accessible price points, with enough long-term durability to hold resale value for secondary buyers.

The impact of the sorting protocol is not uniform across global markets, creating distinct demand signals for wholesale partners. In North America, where hip-hop jewelry remains a top-performing category, retailers report that 28% of items pulled from scrap bins are intact 2000s-style iced pendants and curb chains, creating consistent unmet demand for replica styles to supplement inconsistent secondhand supply. In the EU, where 2026 circular economy mandates require retailers to prioritize resale over material recycling where feasible, sorted resale inventory leans heavily into minimalist silver signet rings and engraved bands, with shoppers prioritizing timeless designs over trend-driven pieces. In Southeast Asian markets, where gold buying is deeply tied to cultural gifting traditions, retailers are sorting out lightweight, contemporary gold pieces for resale to young shoppers, while reporting growing demand for gold-PVD coated stainless steel pieces as a lower-cost, daily-wear alternative to high-priced solid gold.

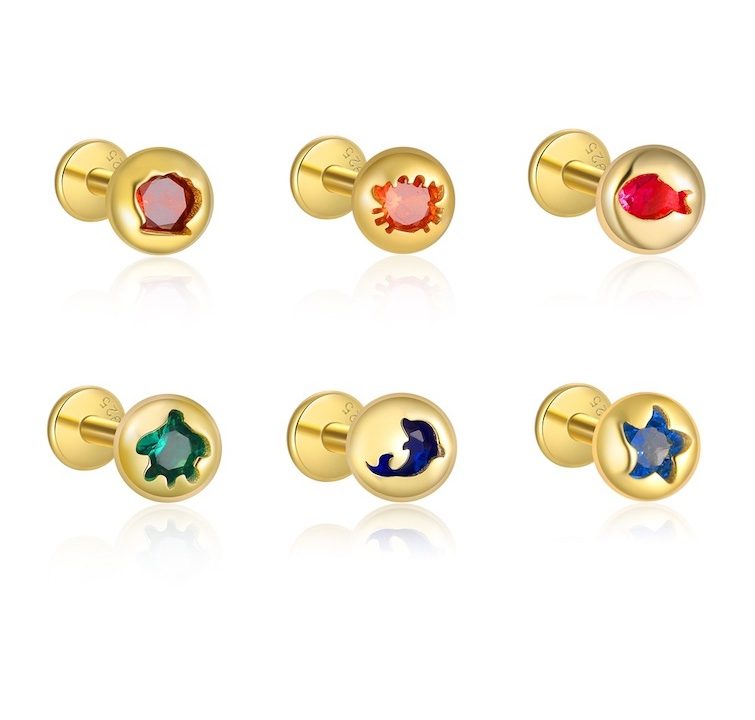
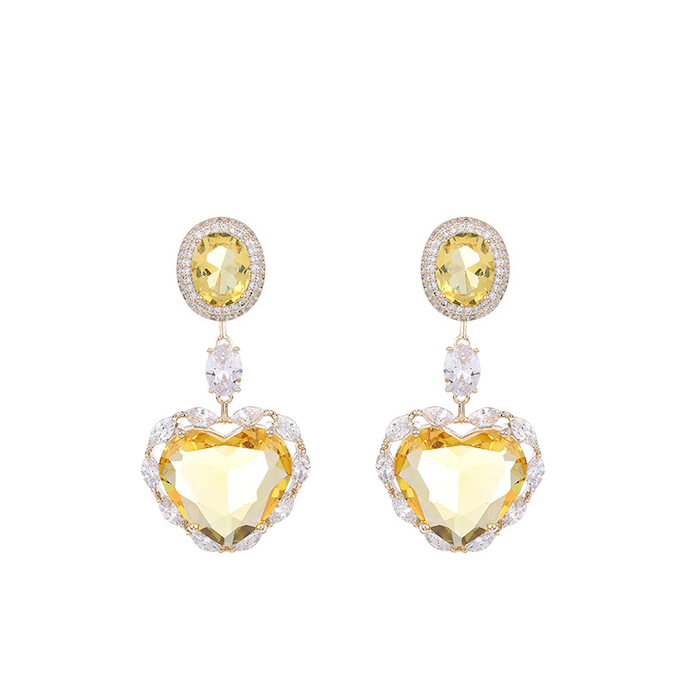
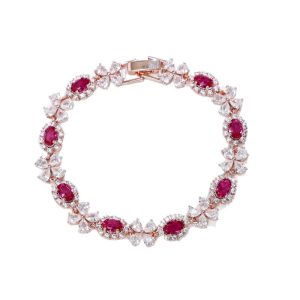
These shifting demand signals are changing what retailers expect from their jewelry supplier, moving away from the old model of bulk, one-size-fits-all generic stock to targeted, flexible inventory aligned with insights gleaned from scrap sorting. As an SGS/ITS certified China jewelry manufacturer founded in 1990, with more than 1000 skilled production workers and end-to-end OEM ODM custom service capabilities, our team tracking order flows across 40+ global markets has recorded a 47% year-over-year rise in 2026 orders for styles that match the high-resale pieces retailers are pulling from scrap piles. Our production lines cover core high-demand materials: 316L stainless steel, 925 silver, and premium cubic zirconia settings, spanning both hip-hop and elevated luxury fashion style segments. Unlike traditional wholesale models that require large minimum orders, our low MOQ structure lets independent retailers and regional chains test small batches of styles identified through their sorting processes, while our full plating and engraving customization options let teams match the exact vintage finishes, custom mark details, and hardware specs of top-performing resale pieces, without the quality inconsistencies of secondhand stock. Our stable wholesale jewelry supply chain also insulates buyers from the volatility of gold refinery supply chains, eliminating the risk of stockouts when scrap buyback volumes fluctuate.
Over the next 18 months, scrap-resale sorting protocols will become standard across 70% of North American and EU jewelry retailers with buyback programs, further blurring the line between secondhand and new custom fashion jewelry inventory. We forecast continued decline in demand for low-quality, thin gold-plated pieces that carry no resale value, while durable, timeless designs in stainless steel and silver will capture a growing share of entry-level jewelry spending. For wholesale buyers, three core strategies will drive margin growth: first, conduct monthly audits of sorted scrap and resale inventory to identify high-performing local styles, rather than relying solely on national trend forecasts for OEM jewelry orders. Second, partner with certified, vertically integrated suppliers that can deliver flexible, small-batch orders across both stainless steel and silver categories, with transparent material testing to eliminate the same misrepresentation risks that cut into scrap buying margins. Third, align inventory selections with regional demand: North American retailers can lean into CZ-accented hip-hop styles to supplement vintage resale stock, EU retailers can prioritize engraved silver pieces aligned with circular policy requirements, and Southeast Asian retailers can stock gold-finish stainless steel everyday pieces to fill gaps between high solid gold price points and consumer budgets.
For too long, the jewelry industry treated scrap processing and new inventory purchasing as entirely separate operational silos. The new retail sorting protocol breaks down that wall, giving retailers unprecedented, real-time insight into exactly what styles, materials, and finishes their local customers will pay a premium to own — and creating a more responsive, resilient wholesale ecosystem that aligns with both consumer demand for circular, long-lasting pieces and retailer bottom-line margin goals.