
2026 marks a structural tipping point for global jewelry buyers, as the role evolves far beyond transactional purchasing to cross-functional strategy balancing fast-shifting consumer values, supply chain resilience, and tightening global regulation. The decades-old playbook of negotiating the lowest per-unit cost for generic, status-driven fine jewelry designs is no longer viable, as sustained shifts in spending power, material costs, and consumer expectations redefine what drives wholesale success across every regional market.
The move away from prestige-centric jewelry is not a fleeting social media micro-trend, but a structural shift rooted in five years of evolving consumer behavior, accelerated by pandemic-era spending priorities and Gen Z’s entry into peak discretionary spending. Industry data shows 31% of 2025 US diamond demand came from self-purchasers, a segment projected to grow to 38% of total global jewelry spend by 2027, as consumers prioritize pieces that reflect personal identity over status signaling. In an era of generic AI-generated designs and mass-produced fast fashion, authenticity and narrative now command a 27% retail price premium, with consumers actively seeking out pieces with clear provenance and personal relevance. Compounding this shift is the universal “scroll to store” purchase journey: while 43% of US consumers report preferring to buy from local, independent jewelers, 78% of those purchase decisions are first influenced by social media content, requiring wholesale assortments to balance in-store wearability with digital shareability.
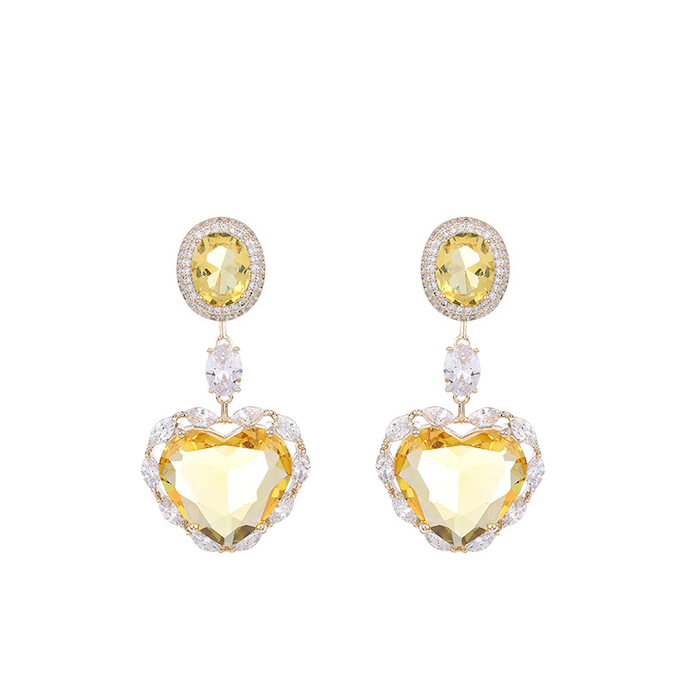
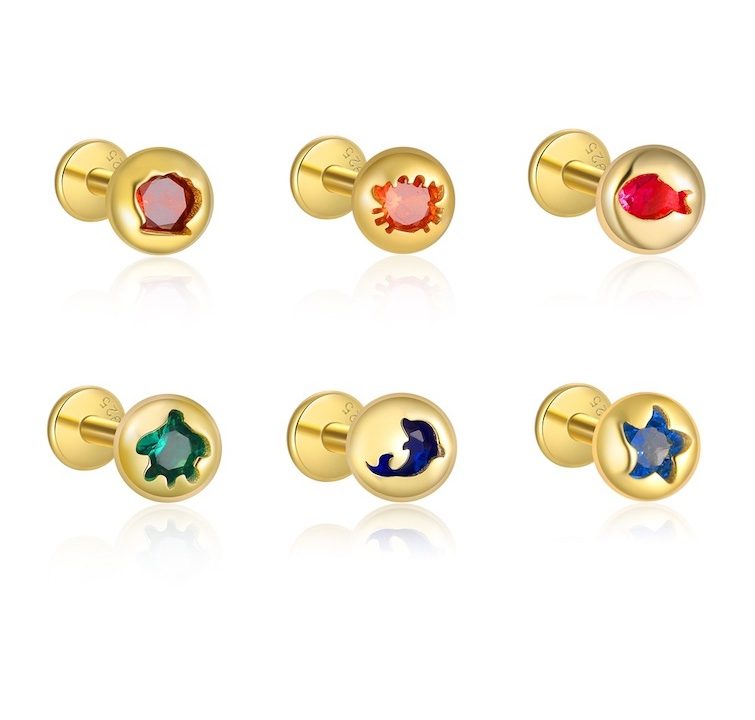
Now representing 30% of global jewelry spending, Gen Z is driving a fundamental rejection of the traditional expectation that jewelry must be a high-investment, lifetime purchase made of solid gold. Record-high gold prices are accelerating this realignment: 2026 global gold jewelry volumes are projected to fall 34% from 2023 levels, as price sensitivity pushes consumers to seek durable, accessible alternatives that do not compromise on style. This shift is driving surging demand for stainless steel jewelry that is waterproof, tarnish-resistant, and capable of holding a full range of bold plating finishes, as well as silver jewelry that hits the affordable luxury price point between disposable fast fashion and high-cost fine gold pieces. Design preferences are shifting in lockstep: traditional white diamonds are now joined by fast-growing demand for champagne, pink, and golden-hued stones, with rubies (up 25% in retail demand) and pearls (up 20%) emerging as top differentiators for assortments. Lab-grown diamonds are now a fully mainstream category, but buyers are increasingly pairing LGDs with stainless steel and silver bases to hit accessible price points for self-purchasers, rather than only setting stones in high-cost gold settings, with bold hip-hop layered pieces and dainty personalized stackables leading demand.

While the self-expression trend is global, material and design preferences vary sharply by market, creating costly pitfalls for buyers who carry a uniform global assortment. In India and the Middle East, solid 22-24K gold remains a core cultural and investment staple, but sustained high prices are driving 21% annual growth in gold-plated stainless steel and silver pieces that replicate traditional intricate designs for younger, budget-conscious shoppers. In the EU and US, regulatory and consumer pressure around ethical sourcing and material safety is non-negotiable, with demand concentrated in nickel-free, hypoallergenic pieces paired with transparent supply chain documentation, plus strong uptake of LGD and cubic zirconia pieces for everyday wear. In Southeast Asia and Latin America, humid climates and casual daily dress codes are driving 19% annual growth in low-maintenance stainless steel fashion jewelry that can be worn during workouts, swims, and daily commutes without tarnishing.

As fashion trends move faster (driven by short-form social media, trend cycles now last 3-6 months instead of the 1-2 year cycles of the 2010s) and geopolitical and logistical risks remain elevated, relying on a single low-cost supplier is no longer a viable strategy. Buyers now evaluate partners on operational reliability (targeting >95% on-time delivery, <4-hour response times), quality compliance, and customization flexibility, rather than unit cost alone. This is reshaping demand for oem jewelry and custom fashion jewelry capabilities, as buyers seek partners that can support small test runs of trend-forward designs without locking them into thousands of units of unproven stock. As a benchmark for this new supplier standard, consider a SGS/ITS certified China jewelry manufacturer founded in 1990: with 1000+ skilled production staff, the firm offers professional OEM ODM custom service across 316L stainless steel, 925 silver, and cubic zirconia jewelry, spanning both popular hip-hop and elevated luxury fashion styles. Its low MOQ structure, full plating and engraving customization options, and stable wholesale supply chain allow buyers to test micro-trends, co-create exclusive story-driven collections for local markets, and replenish core evergreen stock without delays, while built-in SGS/ITS testing and RJC-aligned material traceability (including Kimberley Process documentation for stone components) ensure compliance with REACH, CPSIA, and upcoming EU AMLR due diligence requirements. This type of full-service jewelry supplier eliminates the friction of juggling multiple vendors for production, testing, and customization, a key pain point for buyers navigating fragmented global supply chains.
Looking ahead, gold prices will remain elevated through at least 2028, meaning stainless steel and silver pieces will capture 41% of the entry-level luxury jewelry segment by the end of the forecast period, while demand for personalized, engraved custom pieces will grow 22% annually as consumers seek out authentic, story-driven designs. Compliance barriers will continue to rise, with the EU’s 2027 AMLR rules imposing strict due diligence requirements on all high-value jewelry imports, meaning buyers who do not lock in certified, traceable supply partners now will face costly delays and rejected shipments when the rules take effect. For wholesale jewelry buyers navigating this landscape, three core strategies will drive success: First, build a tiered supplier network, with a reliable primary partner for 60% of core evergreen stock (classic stainless steel staples, basic silver and CZ pieces) to ensure consistent replenishment, plus specialized contingency partners across regions to mitigate geopolitical and logistical risk. Second, leverage low-MOQ custom capabilities to test fashion trends in local markets before scaling, avoiding overstock of short-lived viral designs while still offering fresh, relevant assortments that align with Gen Z self-expression demands. Third, tailor assortments to regional preferences: for MENA and South Asian markets, pair premium gold stock with high-quality gold-plated stainless steel and silver pieces featuring traditional engraved motifs; for EU and North American markets, prioritize certified hypoallergenic materials and traceable stone sourcing to build consumer trust; for emerging Southeast Asian and Latin American markets, focus on durable, waterproof stainless steel daily wear at accessible price points.
Unlike the transactional sourcing models of the past, success in 2026 and beyond will depend on building collaborative, long-term partnerships with suppliers that understand both shifting consumer aesthetics and global regulatory requirements. Buyers that move beyond price-only negotiations to prioritize resilience, customization, and compliance will be best positioned to capture the fast-growing self-purchase segment, while avoiding the supply chain disruptions and compliance penalties that are set to sideline less strategic players in the coming years.